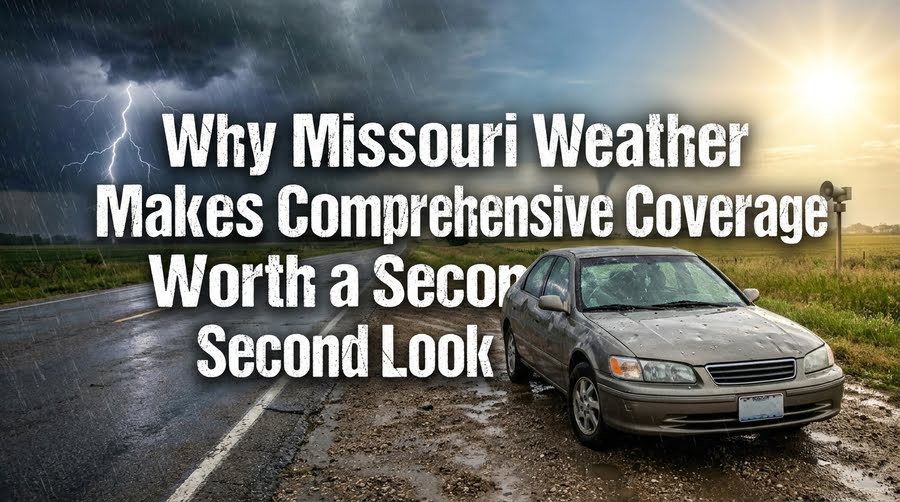
Why Missouri Weather Makes Comprehensive Coverage Worth a Second Look
Missouri gets a bit of everything when it comes to weather. Hailstorms roll through in the spring, ice coats the roads most winters, and tornado season is a real, recurring concern rather than a rare event. If you have ever wondered whether your car insurance actually covers weather damage, or you are trying to decide whether comprehensive coverage is worth the extra cost, this is the breakdown you need.
What Missouri Requires You to Carry
Before getting into weather-related coverage, it helps to know the baseline. Missouri law requires liability insurance of at least:
- $25,000 in bodily injury liability per person
- $50,000 in bodily injury liability per accident
- $25,000 in property damage liability per accident
Missouri also requires uninsured motorist coverage of $25,000 per person and $50,000 per accident, since the state has a notably high rate of drivers on the road without insurance.
Here is the part that catches people off guard: none of these required coverages pay for damage to your own vehicle. Liability only covers damage you cause to someone else. If a hailstorm dents your hood or a tree limb comes down on your windshield during a storm, minimum coverage will not pay for a dime of it.
Where Comprehensive Coverage Comes In
Comprehensive coverage is the piece that actually protects your car from non-collision events, and it is optional in Missouri, not required by law. It typically covers:
- Hail damage, which is common enough in Missouri that many auto body shops run seasonal specials just for it
- Fallen trees or branches during storms
- Flooding
- Fire
- Windshield cracks and glass damage
- Theft and vandalism
If you have ever driven through a Missouri spring and watched the sky turn green, you already understand why this matters here more than in a lot of other states.
Collision Coverage Covers a Different Problem
Collision coverage is often bundled with comprehensive, but it handles something different: damage from an accident, regardless of who is at fault, including hitting a pothole, sliding on ice into a guardrail, or a collision with another vehicle. Missouri winters bring enough ice and snow that this coverage earns its keep more often than people expect, especially in years with a rough freeze-thaw cycle.
Is It Worth the Extra Cost?
For a newer or more valuable car, comprehensive and collision coverage is usually worth adding. If your car got totaled by a hailstorm and you only had liability, you would be paying for a replacement vehicle entirely out of pocket. For an older car with a lower market value, it is worth doing the math. If the annual cost of comprehensive coverage is close to what the car is actually worth, it may make more financial sense to carry liability only and set aside your own savings for repairs.
A simple rule of thumb: if losing the car entirely to a storm, flood, or fire would create real financial strain, comprehensive coverage is worth the added premium.
Keeping the Cost Reasonable
Adding comprehensive and collision does raise your premium, but a few things help keep it manageable:
- Choose a higher deductible. This lowers your monthly cost, as long as you could cover that amount if you needed to file a claim.
- Bundle policies. Combining auto with renters or homeowners insurance often triggers a discount.
- Compare quotes annually. Comprehensive coverage pricing varies more between insurers than liability does, so shopping around tends to pay off.
- Ask about storage or parking discounts. If you can park in a garage rather than on the street, some insurers factor that into hail and theft risk.
When the Upfront Cost Is the Real Obstacle
Adding more coverage usually means a higher deposit to get the policy started, and that upfront cost can be the actual barrier for a lot of drivers, even when the monthly payment itself would be manageable. If that describes your situation, it is worth knowing that flexible options exist. Providers like OCHO help drivers get Missouri car insurance set up without paying the full deposit upfront, breaking that cost into smaller payments timed around payday instead.
Final Thoughts
Missouri’s weather is unpredictable enough that comprehensive coverage is worth genuine consideration, not just an upsell to skip past. Weigh it against your car’s value, shop around for the best rate, and if the upfront cost of adding coverage is what is holding you back, look into payment plans built around that exact problem before deciding to go without.